The call usually comes in August, not January. Your AC quit sometime overnight, the house is already sitting at 84 degrees by nine in the morning, and the technician in your side yard says the system isn’t worth saving. Then somebody says a number out loud and the kitchen goes quiet.
Almost nobody has several thousand dollars parked in checking waiting for a new air conditioner. So once you accept that the old unit isn’t coming back, the question shifts from “can I afford this” to “how do I spread it out without regretting it in year three?”
That’s what AC financing in Elk Grove is for, and there are more paths than most homeowners realize. Some are genuinely good deals. A couple look like good deals and aren’t. Here’s how to tell them apart before you put your name on anything.
Why So Many Elk Grove Homeowners End Up Financing
Our systems work harder than most. From June through September, an AC in the Sacramento Valley can run most of the day just to hold a house at a livable temperature, and that duty cycle wears out compressors and coils faster than the same equipment would on the coast.
Which means replacement arrives on the system’s schedule, not yours. Very few people budget a year ahead for a new condenser. Most find out they need one during the hottest week of the year, when waiting three months to save up isn’t a real option.
There’s an upside worth naming, though. A modern efficient system usually costs less to run than the 15 year old unit it replaces, so part of what you finance can come back through lower summer bills. That doesn’t erase the payment, but it does change the math.
What AC Financing in Elk Grove Usually Looks Like
Nearly every option falls into one of five buckets, and they differ in three things: how fast you can get the money, whether your house is on the line, and what the whole thing costs by the time you’re done paying.
1. Contractor or manufacturer financing
This is the fastest route and the one you’ll be offered on the spot. The installer partners with a lender, you apply at the kitchen table, and approval often lands the same day so the crew can start right away.
The catch lives in the fine print. Plans advertised as no interest are sometimes deferred interest plans, meaning if any balance remains when the promo window closes, the interest gets charged back to day one at a much higher rate. Ask whether the plan is true zero interest or deferred, and get the answer in writing.
2. A personal loan from a bank or credit union
You borrow a set amount, pay the contractor yourself, then make fixed monthly payments for a few years. Rates depend heavily on your credit, and local credit unions are worth a call before you accept whatever the installer’s lender offers.
The advantage is simplicity. Fixed rate, fixed term, no promotional cliff to track, and your house isn’t attached to it.
3. A home equity loan or HELOC
If you’ve owned your Elk Grove home for a while, you may have real equity to work with, and borrowing against it usually carries the lowest rate of anything on this list.
The tradeoff deserves to be said plainly: your home is the collateral. Miss enough payments and the lender has a claim on the house. These also take the longest to set up, often several weeks, which rules them out during an active breakdown.
4. A credit card with a promotional period
A card with a genuine introductory zero interest window can work if you’re confident you’ll clear the balance before it ends. If there’s any chance you won’t, the rate that kicks in afterward is usually the highest of anything here.
5. Paying from savings
Not financing at all, but it belongs here because it’s the cheapest path when available. Plenty of homeowners split the difference: pay a chunk up front, finance the rest, and keep the balance small enough to clear in a year or two.
What to Check Before You Sign Anything
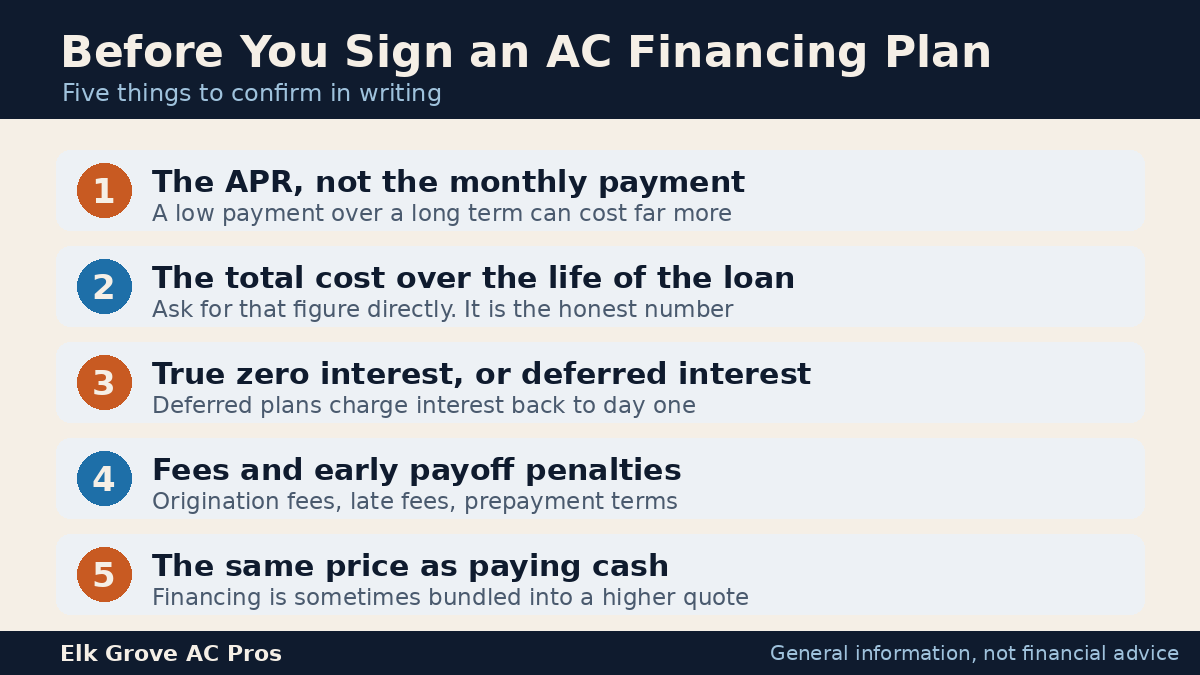
Salespeople quote monthly payments because a small number feels manageable. Lenders quote APR because that’s what the loan actually costs. You want the second number. Five things to pin down before you agree to anything:
- The APR, not the monthly payment. A low payment stretched over a long term can cost far more than a higher payment over three years.
- The total you’ll pay over the life of the loan. Ask for that figure. It’s the honest number.
- Whether a promotional rate is true zero interest or deferred, and the exact date it closes.
- Origination fees, late fees, and any penalty for paying the loan off early.
- Whether the equipment price matches what you’d pay in cash. Financing is sometimes bundled into a higher quote.
One habit saves people a lot of grief: get the equipment price and the financing terms as separate line items on the same document. A contractor who won’t break those out has told you something useful.
Rebates and Credits Can Shrink What You Borrow
Before you decide how much to finance, find out how much you actually need to. Sacramento area homeowners have real programs available, and they cut the loan, not just the sticker price.
SMUD has offered real rebates on qualifying high efficiency heat pump systems, generally requiring specific efficiency levels and installation by a contractor in their network. There’s also a federal energy efficient home improvement credit for qualifying equipment, claimed at tax time rather than at purchase, plus statewide electrification incentive programs.
Two cautions. Amounts, efficiency thresholds, and eligibility rules change every year, so confirm current details with SMUD and the IRS energy efficient home improvement credit page rather than trusting a number in any article, including this one. And this one bites people: start the rebate paperwork before installation day, since some programs require preapproval or a participating contractor, and you can’t add either after the crew leaves.
Common Mistakes to Avoid
Almost every regret about AC financing in Elk Grove traces back to a handful of moves, and all of them are avoidable.
Deciding under pressure on the hottest day of the year. Heat makes people sign things. If you can get through a night with fans, a window unit in one bedroom, or a stay somewhere cool, do that and read the paperwork with a clear head in the morning.
Taking the first plan offered without shopping the rate. The installer’s lending partner might be competitive, or it might sit several points above what your credit union would give you. One phone call tells you which.
Stretching the term just to hit a payment target. A ten year loan on equipment that lasts twelve to fifteen years in our climate leaves almost no cushion, and you’ll still be paying when it needs its first real repair.
Financing the wrong size system because nobody ran a load calculation. Wrong capacity costs you every single month, no matter how good the loan terms looked. Ask how the size was determined before anyone talks about payments.
Never sign a contract with blank spaces in it, and don’t accept a verbal promise about a rebate, a warranty, or a rate. If it matters, it goes on the document.
How to Get Ahead of This Before Your System Quits
The homeowners who get the best terms are almost always the ones who shopped before they had to.
If your system is past twelve years, needing annual repairs, or struggling to keep up on 105 degree afternoons, treat replacement as a project you’re planning instead of an emergency you’re dreading. Get two or three quotes in spring or fall, when installers aren’t buried and you have room to negotiate. Ask each one about financing while you’re still comparing calmly, and check your credit score, since it drives every rate you’ll be offered.
If you’re not sure it’s time yet, our guide on deciding between repair and replacement walks through the signals, and the AC replacement cost guide gives you a sense of the range you’d be financing.
Doing this before your system fails is the single biggest thing that improves your options. Nobody negotiates well at 84 degrees indoors.
Key Takeaways
- Five paths: contractor plans, personal loans, home equity borrowing, promotional credit cards, and savings. Speed, risk, and total cost differ across all of them.
- Compare APR and total cost, never the monthly payment alone.
- Ask whether a promotional zero interest offer is deferred interest, and get the answer in writing.
- Home equity borrowing is usually the cheapest and also the only option that puts your house at risk.
- Check SMUD rebates and the federal credit first, since they lower what you need to borrow.
- Shop in spring or fall if you possibly can. Emergency decisions cost more.
Frequently Asked Questions
Is AC financing in Elk Grove worth it, or should I just wait and save?
If your system is dead in July, waiting isn’t on the table, and a reasonable loan beats a summer without cooling. If it still works and you’re planning ahead, saving part of the cost first and financing a smaller balance costs less overall.
What credit score do I need?
It varies by lender, and there’s no single cutoff. Stronger credit means better rates and longer promotional windows. Options exist for lower scores, but rates climb fast, so compare at least two lenders instead of taking the first approval.
Can I finance a repair instead of a full replacement?
Often yes, though smaller amounts usually run through a credit card or a short contractor plan. If repairs keep stacking up year after year, price out replacement before you finance another one.
Does financing affect my rebate eligibility?
Generally no. Rebates and credits hinge on the equipment and the installer, not how you paid. Confirm with the program, since rules vary.
Ready to Talk Numbers on a New System?
Planned upgrade or a system that just gave out, the first step is the same: know what the work involves. Our AC replacement and AC installation pages show what a proper job includes, so you can compare quotes side by side.
Elk Grove AC Pros is a local HVAC information and lead request service. We are not a licensed contractor, and this article is general information, not professional HVAC advice or financial advice. Loan terms, rebate amounts, and program rules change, and a licensed local pro should assess your specific system and home before you commit to anything.
Want a starting point? Request a free, no pressure quote and we’ll connect you with a licensed local pro serving Elk Grove and the greater Sacramento area.